Insurance Fraud Has a New Set of Tools
We once had good reason to trust what we could see and hear. A photograph seemed to show what really happened. A familiar voice on the phone seemed trustworthy. A polished document with a company logo looked official. Artificial intelligence has made each of those signals easier to imitate. With widely available tools, a dishonest person can alter claim photos, create receipts, copy a voice, or generate a convincing message in minutes.
That does not mean every edited image or automated message is fraudulent. AI has legitimate uses throughout the insurance industry. Fraud begins when someone intentionally provides false information, hides an important fact, or impersonates another person for financial gain. The current technology is new, but the goal is familiar: to create enough confusion or urgency that someone acts before checking the story.
How AI Can Appear in an Insurance Scam
Some schemes target insurance companies directly. A claimant might digitally add damage to a vehicle in a photograph, change the date or amount on an invoice, or submit images of property that was never owned. Synthetic identities can also combine real and invented information to apply for coverage or make claims.
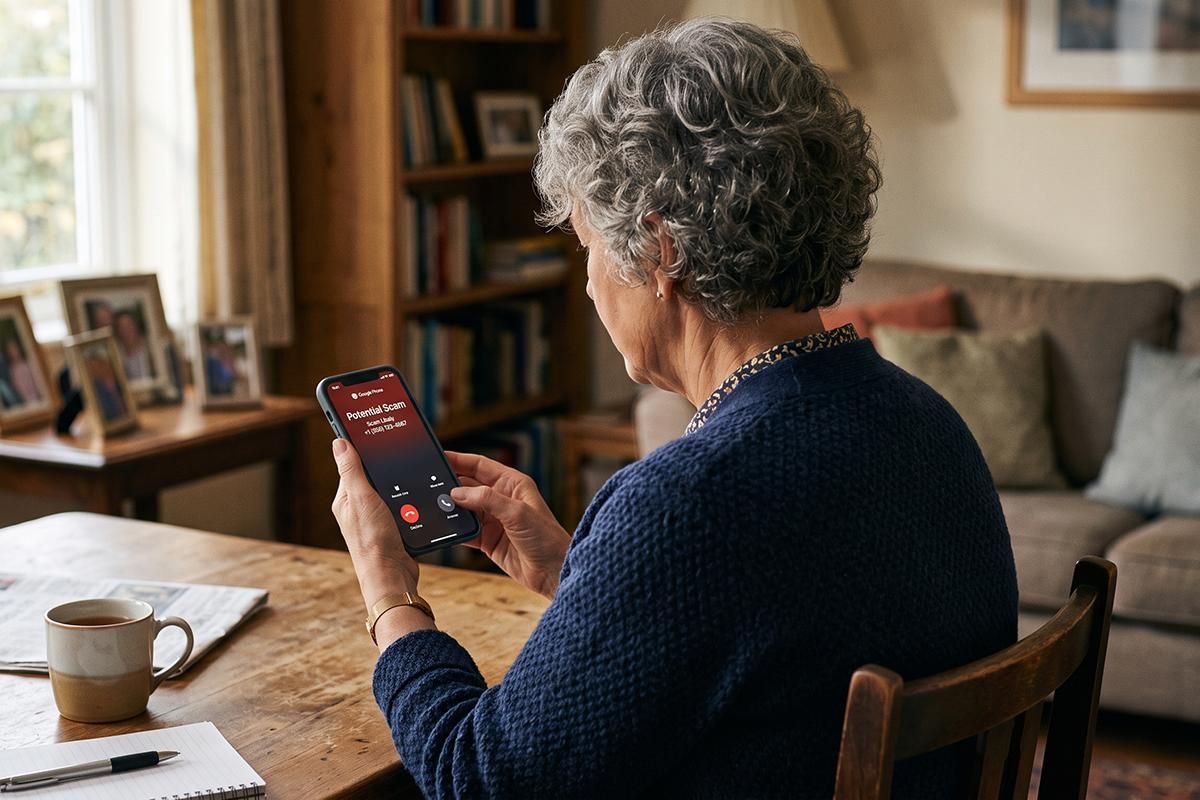
Other schemes target policyholders. A scammer may pose as an agent, adjuster, insurance carrier employee, medical provider, or beneficiary. AI-generated audio can make a caller sound like someone you recognize. A fake website may closely resemble an insurer's portal and collect login credentials, Social Security numbers, or payment information. In these situations, the consumer may be the victim even though the message appears to be about an insurance policy or claim.
Warning Signs to Watch For
AI can improve the disguise, but many scams still rely on familiar pressure tactics. Be cautious when a caller or message:
- Creates an emergency and demands an immediate response
- Asks you to keep the conversation secret or avoid contacting your agent
- Requests payment by gift card, cryptocurrency, wire transfer, or an unfamiliar app
- Sends a link to a website with a misspelled or unusual address
- Asks for a password, security code, or full financial account number over the phone or email
- Mentions policy activity, a claim, or a beneficiary change you do not recognize
Do not depend on visual glitches or an unnatural voice to expose a fake. AI-generated material is becoming more convincing. The safer approach is to verify the request through a separate, trusted channel.
Build a Simple Verification Habit
If someone contacts you unexpectedly, pause. Do not use the phone number, email address, or link included in the message. Instead, find the carrier's contact information on your policy documents, insurance card, official app, or a website address you enter yourself. You can also call us to help verify the information.
Protect online accounts with unique passwords and multifactor authentication when it is available. Review policy statements and claim notices, and question changes you do not recognize. Limit the personal details you share publicly, since names, birthdays, family relationships, travel plans, and voice recordings can help scammers make an impersonation more believable.
Keep Your Own Claim Record Clean
AI editing features are now built into many phones and photo apps. When documenting legitimate damage, keep the original images and don't use filters, object removal, background replacement, or other changes that alter what the photo shows. Save receipts, estimates, emails, and repair records in their original form. If a photo is blurry or does not capture the damage clearly, take another one instead of trying to reconstruct the scene digitally. Ask the adjuster what documentation is needed, and describe any edits or annotations you make. A clear record can protect your credibility and help the claim move forward without unnecessary questions.
What to Do If Something Feels Wrong
Stop communicating with the suspected scammer and save the email, text, voicemail, website address, or payment details. Contact your insurance carrier through a verified number and explain what happened. If money or account information may be involved, contact the appropriate financial institution promptly. You may also need to change passwords, monitor your credit, and report the incident to law enforcement or a consumer protection agency like the FCC.
A Real Relationship Is a Useful Safeguard
Technology will continue to change, and it may become harder to judge a message by appearance alone. A trusted insurance professional gives you a known person to contact when a request does not make sense. If you receive an unexpected insurance message or want to confirm how your carrier normally communicates, reach out to our office. We can help you slow down, verify the source, and decide on a sensible next step.